Palm Sinks to a Twelve-Week Low
Key takeaway: Benchmark December palm oil on Bursa Malaysia closed at 4,533 ringgit a tonne on 2 October, its lowest close since 10 July and a second weekly loss of about 3%. September exports fell 17% to 29% from August by cargo surveyor estimates, and traders expect end-month stocks to be large.
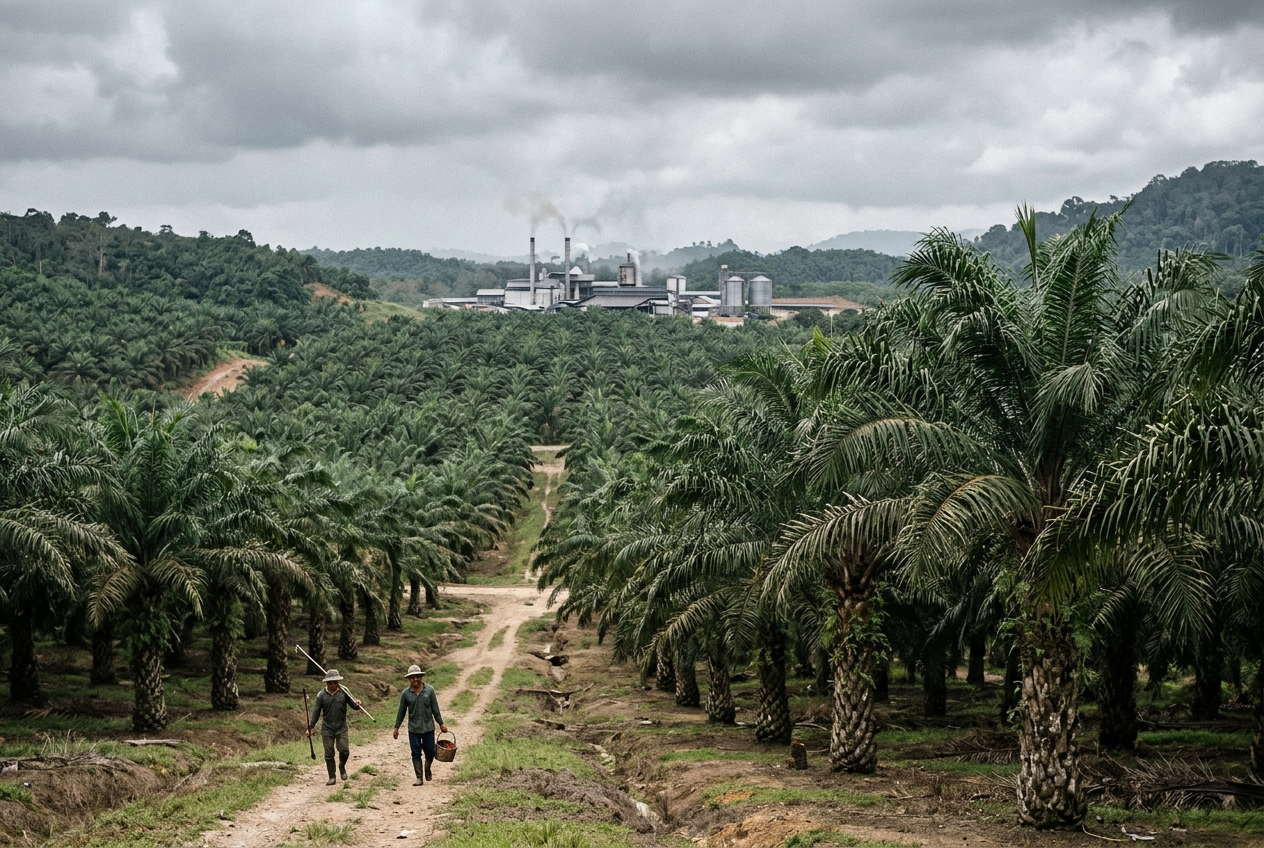
Palm oil ended the first week of October at a level it last saw in early July. The December contract settled at 4,533 ringgit a tonne, down 21 ringgit on the day, after touching a 13-week low earlier in the session. The week's decline was close to 3%, following a loss the week before.
Nothing dramatic triggered it. This was a slow grind lower, driven by the plain arithmetic of a market that is producing more than it is shipping.
September exports fell off a cliff
Cargo surveyor estimates put Malaysia's September palm oil shipments 17.1% to 28.8% below August, depending on the surveyor. The spread between the two estimates is wide, but both point the same way. An export drop of that size in a peak-output month leaves product with nowhere to go except storage.
Output is the other half of the story. A Kuala Lumpur trader said September production rose sharply, and that the combination of weak shipments and stronger output is pushing end-month stocks above 3 million tonnes. That figure is a trader's expectation, not an official number. The Malaysian Palm Oil Board publishes September stocks in mid-October, and that release will settle the question. For context, the board's August report showed stocks at the highest in several months, so the trend was already building before September began.
Indonesian shipments offered little relief. Exports from January to August totalled 16.13 million tonnes, about 0.4% lower than the same period last year. Indonesia is not flooding the market, but it is not tightening it either.
Soyoil gives no lift
Palm usually finds support when soyoil rallies, because buyers swap between the two. That did not happen this week. CBOT soyoil was close to flat on the day, so there was no external tailwind to offset the weak export numbers. With Chicago idle, Kuala Lumpur had to carry the whole adjustment itself.
What the forward view says
One of the market's most closely followed analysts expects palm to stay within 4,500 to 5,000 ringgit through December. The reasoning is that high inventories will cap rallies even though lower output is expected in 2027 as El Niño works through the trees.
That is a sensible reading of the calendar. Dry-weather damage to palm shows up with a lag of many months, so a 2027 supply problem does little for prices while tanks are filling in 2026. Futures traders know this, and they are paying for the stock they can see.
On the charts, technical analysts flagged support at 4,478 ringgit and then 4,445. A close below the first would put the market near the bottom of the analyst's range.
The India connection
For Indian buyers, softer palm is welcome. The government's September cut in basic customs duty on edible oils lowered landed costs, and a falling flat price adds to that. Festival demand is the obvious reason to restock. The open question is whether palm wins the extra tonnes or whether soybean and sunflower oil, which also benefited from the duty change, take most of them. A wider discount of palm to soyoil is what would bring refiners back, and the current slide is moving the spread in that direction.
There is a second-order effect worth watching. If Indian buying revives on lower prices, it can shorten the stock build that Malaysia is facing. Port arrival data for October will show whether that is already happening.
What to watch next
The MPOB September report is the next hard data point. A stock number near or above the trader's 3 million tonne expectation would confirm the bearish case and likely test support. A smaller build would suggest the export weakness was partly a timing issue and could trigger a sharp short-covering bounce. Exports for the first days of October, due from surveyors in the coming week, will show whether demand has stabilised.
Our view is that the market is rangebound with a downward bias until the stock cycle turns, probably around the year-end rainy season. The 2027 supply story is a reason to buy dips later, not a reason to hold back selling now. This is market analysis, not investment advice.
Meet the market at GLOBOIL India 2026. Stock builds, export swings and the palm-soy spread decide how India buys. GLOBOIL India 2026, the 29th edition of the world's leading edible oil and agri-trade conference, was held 29 September – 1 October 2026 at The Westin Mumbai Powai Lake, Mumbai, where buyers, refiners, origin sellers and policymakers discussed exactly these questions. Follow GLOBOIL for post-event insights and plan for the next edition.