A Prairie Surplus
Key takeaway: Agriculture and Agri-Food Canada raised its 2026/27 canola ending stocks forecast to 1.979 million tonnes from 1.504 million tonnes, a jump of about 32% in one month. A bigger Canadian surplus weakens cost support for rapeseed oil and adds to a vegetable oil complex already struggling with heavy palm supply.
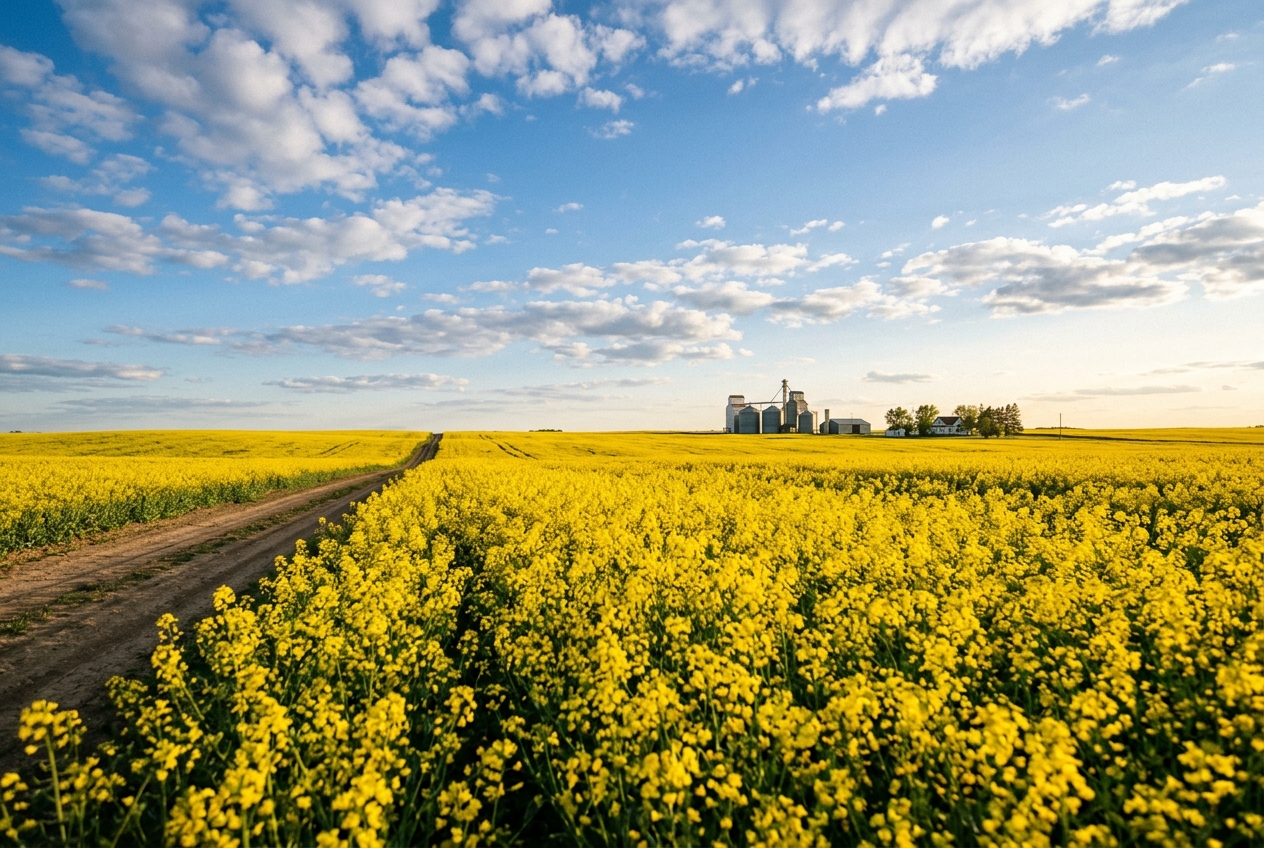
The world's largest canola exporter has more seed than it expected. In its September outlook, Agriculture and Agri-Food Canada (AAFC) lifted projected 2026/27 ending stocks by roughly 475,000 tonnes to 1.979 million tonnes. It also revised the closing balance for the 2025/26 season up by 175,000 tonnes to 1.90 million tonnes.
The two revisions compound. More seed carried into the new season, along with a downgraded view of how fast it will move, leaves Canada looking at a much looser balance sheet than it did at the end of August.
Why Canada's canola carryout jumped
The 2025/26 revision follows Statistics Canada's July 31 stocks survey, which put total canola stocks at about 1.9 million tonnes, up 18.9% from a year earlier. On-farm stocks more than doubled to 837,000 tonnes while commercial stocks fell 12.8% to 1.1 million tonnes. The detail matters. Seed held on farms is seed that farmers chose not to sell at recent prices, and it now sits over the market as the new harvest arrives.
On top of that opening position, Canadian growers planted a large canola area this spring. With harvest under way across the Prairies, the market now has to absorb old-crop carry and new-crop volume together.
Canada's canola is split between two outlets: domestic crushing, which has grown fast on the back of North American renewable diesel demand, and seed exports, where trade frictions have narrowed the list of willing buyers. When exports lag, the balance falls on crushers and on stocks. AAFC's revision suggests the agency sees more of it ending up in stocks.
Price impact on rapeseed and rapeseed oil
The immediate effect is weaker cost support across the rapeseed chain. ICE canola futures have stayed stuck in a narrow range since early September, with the November contract trading in the low CAD 820s per tonne late last month. Rallies have stalled each time crude oil or the broader vegetable oil complex has turned lower.
A bigger carryout makes that range harder to break on the upside. It also feeds into Europe, where rapeseed values take direction from Canadian and Australian export supply. Ample seed means crushers can source cheaply, and that tends to flow through to rapeseed oil offers.
Meal is the other side of the trade. If Canadian crush runs at high rates to work through surplus seed, more rapeseed meal comes onto the market. Feed buyers gain, but crush margins come under pressure because oil has to carry a larger share of the value.
Weather risk remains in Australia and Europe
The surplus picture is not uniform. Eastern Australia's canola belt has gone close to three weeks without meaningful rain during flowering and early pod fill, according to crop weather monitoring. Western Australia, the largest producing state, is in better shape. Parts of Western Europe are also dealing with very dry seedbeds for newly sown winter rapeseed.
These are risks to watch rather than a shortage today. Canada's extra tonnes give the market a buffer, and a weather problem elsewhere would more likely narrow the surplus than reverse it.
What it means for India
India imports very little canola oil directly. Its exposure is indirect, and it comes through two channels.
The first is the overall vegetable oil price level. Rapeseed oil competes with soybean and sunflower oil in Europe and elsewhere. A cheaper rapeseed complex pushes those competing oils to look for other buyers, and India, with import duties cut on 24 September, is the obvious destination. That adds to the downward pressure on the crude soft oils that make up a growing share of India's import basket.
The second is mustard. India's rapeseed-mustard crop is sown from October into November. Weak international rapeseed and rapeseed oil prices limit how far domestic mustard oil can rise without losing ground to cheaper imported oils. Combined with lower import duties, that raises a planting question for growers deciding how much area to commit this rabi season, and it bears directly on the self-sufficiency goals of the National Mission on Edible Oils.
Outlook
Our read is that rapeseed and rapeseed oil remain followers in the current market rather than leaders. Canada's revision removes a reason to expect a supply-driven rally before year-end. The direction of canola now depends more on crude oil, North American biofuel demand and the palm cycle than on Canadian supply alone.
The next markers are AAFC's October update, Statistics Canada's production estimates as the harvest wraps up, and the Australian harvest from November. Any sign of stronger Canadian export pace would be the first hint that the surplus is being worked down. This is market analysis, not investment advice.
See the whole oilseed picture at GLOBOIL India 2026. From Prairie canola to Indian mustard, oilseed balance sheets are global and the pricing is local. The 29th edition of GLOBOIL India, the world's leading edible oil and agri-trade conference, brings origin, crush and import specialists together at The Westin Mumbai Powai Lake, Mumbai, 29 September – 1 October 2026.